
How to calculate and fix excess Roth IRA contributions
The Roth IRA excess contributions can be fixed and you have a few options on how to do it. The three options for fixing the excess contributions are removing the excess contributions, moving them to the following year, or recharacterizing (transferring) the excess contribution and net income attributable (the gains associated with the excess contribution) to a traditional IRA.
Three Methods to Fix Roth IRA Excess Contributions
- Remove excess contributions to a non-retirement account (a regular brokerage or investment account).
- Absorb (move) the contributions to the following year.
- Recharacterize the excess to a traditional IRA.
If you made multiple contributions, the last amount contributed is considered the excess contribution. If you contribute to both a Traditional IRA and Roth IRA for the same tax year, the excess is considered to have occurred in the Roth IRA first.
If you file your taxes on time without withdrawing the excess contributions, you can still fix it within 6 months of the due date of your tax return, even without filing an extension. However, if you do not fix it by the April filing deadline, you can't use the recharacterization method.
6% Penalty (excise tax) and AVOIDANCE
Each year that you do not fix the excess contributions, you will be subject to a 6% excise tax on the excess contribution until you fix it or the contributions have been absorbed.
Pro Tip: If you fix your excess contributions before your tax filing deadline including extensions, you will not be subject to the 6% penalty. You DO NOT need to file an extension to qualify for this deadline, which is usually October 15th.
The excess contributions are absorbed if the following year's amount you qualify to contribute is equal to or greater than the amount of your excess contribution. However, you will still pay the 6% penalty in the first year for this scenario.
For example, if you over contributed $6,000 to your Roth IRA this year but you qualified to make the full $6,000 contribution next year, that $6,000 would count as the contribution. You would still have to pay the 6% penalty for the year the excess contribution was not fixed.
In some instances, this may be the most desirable outcome. Fixing an excess contribution might be more work than it's worth. In the above example, the penalty on the excess amount is $6,000 x 6% = $360.
If the amount is not absorbed, the 6% penalty will continue each year until you fix the excess contribution.
How to calculate your Modified Adjusted Gross Income for Roth IRA Income Limits
Use the following worksheet to calculate your modified adjusted gross income to determine your Roth IRA contribution income limit. The second worksheet will help you calculate your Roth IRA contribution limit.

How to calculate your Roth IRA contribution limit
Use the following worksheet to calculate your Roth IRA contribution limit. If you are between the income phaseout amounts listed under the Roth IRA Income Limits, this worksheet will help you calculate your reduced amount.
The Roth IRA Income Limits are below this worksheet.

Roth IRA Income Limits
| Filing Status | 2022 Roth IRA Income Range | 2023 Roth IRA Income Range |
|---|---|---|
| Single | $129,000-$144,000 | $138,000-$153,000 |
| Married Filing Jointly | $204,000-$214,000 | $218,000-$228,000 |
| Married Filing Separately | $0-$10,000 | $0-$10,000 |
Method #1 - Removal of Roth IRA Excess Contributions
00:00:00:06 - 00:00:23:19
Over contributed to your Roth IRA and now you need to fix it. So I'm going to go over some rules that you need to be aware of. And then I'm going to go over for examples to help you figure out how to calculate it, including a link to a worksheet that's going to make it a lot easier and a blog post that I'm going to go through So you have all the tools and resources ready to fix this.
00:00:23:26 - 00:00:43:27
What's going on, guys? Welcome back to the Channel or did your first time on our channel. Welcome to the Channel. My name is Travis Sickle. And let's go ahead and get right into it. So there's a couple of things that you need to be aware of. The method I'm going to use in this video. Means and requires that you're doing this fix before you're filing your taxes, including extensions.
00:00:43:28 - 00:01:06:02
Now, if you've already filed your taxes, but you haven't hit the October 15th deadline, for your tax filing year. Guess what? You could still do this fix. You can still do an amendment. And if you filed an extension, you can still fix it. Even if you didn't file an extension. You can still fix it just as long as you submitted your taxes on time.
00:01:06:06 - 00:01:27:24
That is the only thing you need to do in order to complete this fix. So that is rule number one in order to even qualify to do this method. We're going to take the money out of the Roth IRA or you can recharacterize it over to the traditional IRA. Either way, the math that I'm going to go through is going to help you calculate.
00:01:28:02 - 00:01:49:26
So, you know, exact tally how much you either need to take out or recharacterize. Now, the difference here is if you take the money out of the Roth IRA, the growth portion that's going to be attributable also called the net income attributable will be taxable as ordinary income. In addition, you're going to get a 10% penalty if you're under the age of 59 and a half.
00:01:50:04 - 00:02:21:09
Now, if you recharacterize it, you can avoid all of that. So you're not going to have a penalty. If you can qualify into a recharacterization over to your traditional IRA, and if you've heard about the 6% excise tax penalty on the excess contribution that is not going to apply in how we're going to do the calculation that would only apply is if we didn't do this calculation and fixed the excess Roth contribution before our October 15th deadline.
00:02:21:09 - 00:02:42:19
Now I say October 15th, it's usually October 15th, but if it falls on a weekend or holiday, they just move that date around. But it's usually October 15th as long as you file your taxes or filed an extension. And I'm going to say it one more time. If you already filed, you don't have to actually file your extension in order to qualify for this extension on this fix.
00:02:42:27 - 00:03:05:12
So with your taxes, the automatic extension, you actually have to file something to get it In this instance, you do not. But if you didn't file your taxes and you still have this fixed and you're after the April 15th deadline. That's right. The April 15th deadline, then you're not going to qualify for this extension and you have to move on to a different way in order to fix it.
00:03:05:16 - 00:03:23:20
But if you're in this window then you can still watch this video and use this method. So before we go ahead and get started, let me go ahead and pull up some resources on the blog post to show you what you need. And you're going to have it all in front of you, including the worksheet, which will help us work through these four examples that I'm about to go through.
00:03:23:21 - 00:03:43:08
So here's my blog and the post that I'm talking about is how to fix the excess Roth contributions. And if we just scroll down a little bit, you'll see I have a spot about the 6% penalty and how to avoid it. But here is what you need to know. You need to know the modified adjusted gross income for your Roth IRA to figure out what your excess contribution is.
00:03:43:08 - 00:04:02:17
And this is where it's really going to start. So once you figure out your modified adjusted gross income and I have the worksheet right here, then you're just going to scroll down to figure out what your phaseout is. So this first one figures out what your income is, your modified adjusted gross income. Then you're going to apply this to the phaseout.
00:04:02:17 - 00:04:24:23
Now, if you're below the phaseout and I have them right here. The Roth IRA income limits, these are modified adjusted gross incomes. But if you're single for 20, 21 and you earn under 125,000, you're not going to have this issue although you could still have an excess contribution. You can still make the full $6,000 contribution. But you could see the phaseout goes up to 140,000 for singles.
00:04:24:29 - 00:04:42:03
So if you're right in the middle of this, then you're going to want to use this worksheet on the phase-out to figure out how much you would qualify for and which part was your excess contribution and so if you scroll down even further, you're going to see this links to downloading the worksheet and that is what I'm going to go through.
00:04:42:08 - 00:05:02:20
But if you also like to read about it, you can go to this blog post and I go step by step on all the different sections on how to fill out this worksheet. So let's go ahead and bring up the worksheet. And let's go through our first example. So the first example that I'm going to go through and I'll go ahead and pull it upright on the screen for you, I find that this is the best way to do it.
00:05:02:25 - 00:05:23:00
Just because there are so many different nuances. So I chose four examples where I drew out four examples to hopefully make this a little bit easier. So you can follow along. So let's say that on January 1st of 20, 21 you had a Roth IRA that had $500 in it and there was no growth. So let's say we had no growth until February 1st.
00:05:23:00 - 00:05:53:13
2021, no growth and we made it a contribution of $500. Now, this is our first contribution. This was already previously contributed in prior years. So it's $500 and then we contributed $500 bringing our total to $1,000. Now we had some growth in my example and it grew to $2,000 on 4/1/2021. And then we had a rollover contribution of $4,000 on 5/1.
00:05:53:21 - 00:06:21:03
And then so that means we had $6,000 or 2000 plus our four was our six and then our $6,000 by January 15th grew to $8,000 So let's go ahead and take a look at the worksheet here and we could see the excess contribution. Now, these are the numbers that we need to understand here. So the excess contribution here wise is going to be the full amount.
00:06:21:03 - 00:06:41:07
We're just going to assume that we didn't qualify for anything So that means it's $500. And let me bring up this really quickly so you can see it. $500 was our only contribution. This is a rollover contribution. This was our only contribution into the Roth IRA. So this means that we're going to put in our excess of $500.
00:06:41:12 - 00:07:12:06
Now, if we look at our numbers here, we can see that $8,000 was on January 15th, 20, 22. But it is the date that we're going to remove it. So that's what we want to take a look at. This is actually the closing balance is what you should be using of yesterday. So after 4:00 is when you want to run this math and you're going to look to what the closing price was of all the positions add up all of the positions, including the cash in that single Roth IRA that you have the excess and that is what you need to look at.
00:07:12:07 - 00:07:29:08
You need to look at the Roth IRA that has the excess contribution. You have three or four Roth IRAs. You're not going to aggregate them. You're not going to look at all of them across the board, just the ones that you made the excess contributions to. So if you have one that you made the excess contribution to, that's the one that you're going to have to pull it from.
00:07:29:13 - 00:07:49:20
You can't pull it from another Roth IRA or even bother with the math on the other Roth IRAs because they're not included in this calculation. It is only for the Roth IRA that you made the excess contribution to. So moving on to the next cap into amount of any withdrawals, we didn't make any of those account balance immediately before the excess was made was $500.
00:07:49:26 - 00:08:17:27
And we could see that again. Right here that we started with 500 contribute 500. There was no growth. So this is the balance right before our excess was made. So that means a number for the amount of the excess contribution and all subsequent contributions made before the excess removal. So that is going to be 40 $500. The reason it's going to be 40 $500 is because our excess was 500, but we also had a rollover contribution of 4000.
00:08:17:28 - 00:08:41:19
Now this wasn't an excess, it was a rollover contribution but the amount that we have to add up includes the contributions and all subsequent contributions. So $500 was our excess. What came after it is 4000 that's what we need to calculate. So that's where we're getting $4,500. Now for number five, any time deposit penalties that will be applied due to the excess removal that is going to be zero.
00:08:41:19 - 00:09:01:24
It's likely to be zero. Those are any penalties that you might have associated with things like a CD or an annuity. Or basically those are the only two that come to mind. If you have any charges for liquidating your assets in order to take them out of the Roth IRA, that would be included on any time deposit penalties.
00:09:02:05 - 00:09:30:00
But for most people, they're probably not going to have that. So just put zero in almost every example I run or anything I encounter with an excess contribution, it's always zero. So that's what we're going to put there. So if we scroll down, we can see the math right here on the formula. And our excess contribution was $500 and our total earnings was $3,000 or adjusted opening balance.
00:09:30:09 - 00:10:02:09
So we're opening balance was $500. But our adjusted opening balance and you can see the definition right here, the balance of the account immediately before the excess contribution plus the excess contribution and all subsequent contributions. So we're basically taking that 4000, the $500 and adding it to the original $500. And that's where we're getting $5,000 from. So doing this math, our net income attributable is $300.
00:10:02:18 - 00:10:22:10
So we need to take out the excess plus our net income attributable, which is $800. So that was example number one. Now we're going to go through example number two and let me go ahead and pull it up on the screen for you. So on January 1st 20, 21, I'm keeping that number the same. $500. It also did not grow.
00:10:22:10 - 00:10:51:15
So on February 1st 20, 21, we made an additional contribution. Contribution $500, total balance, 1000 same math. This is growing to $2,000. And then we're realizing our mistake on January 10th, 20, 22, but we had another thousand dollars in growth. So let's go ahead and walk through this on the screen. Let me go ahead and Xerox some of these numbers and we can go ahead and plug what we want.
00:10:51:15 - 00:11:13:20
And I would suggest if you're going through this, that you zero out all of the numbers just to start fresh. You don't make any mistakes. Our excess contribution amount. So our excess contribution, we only made one contribution of $500. So it's going to be $500. So we'll put $500 in there, our balance as of the date of withdrawal.
00:11:13:29 - 00:11:44:06
So the balance as of the date of withdrawal is $3,000 because we're going to say this is the balance was on yesterday's close and then we're going to fix it the following day. So that's going to be $3,000 So we'll put in $3,000 and then the amount of any withdrawals we have none account balance immediately before the excess was made, immediately before was still our $500 right before and then the amount of the excess contribution and all subsequent contributions made before the excess removal.
00:11:44:07 - 00:12:06:28
Now we did have any other contributions, no rollovers, no additional contributions. So we're going to put in $500 and then any time deposits will put as zero. And there you go with our math again. So we had $500 for the excess contribution and 2000 was our total earnings and 1000 was our adjusted opening balance. So just one more time $500.
00:12:06:28 - 00:12:32:11
Plus you're taking all of the excess contributions and all subsequent contributions and adding it as our opening balance right back there on our $500. So that's where we're getting that math from. And then we have a total net income attributable after reading all those math, 4000 bucks and total amount to be withdrawn. 1500 dollars. Why excess was $500, but our net income attributable was $1,000.
00:12:32:21 - 00:13:00:21
So I think the point I wanted to make here was and drawing out this example was that even if there's growth after 1231 of the taxable year, it still is going to be attributable until you fix it. So you need to make sure that you're fixing it before your tax filing deadlines, including extensions. So that is why I wanted to point out that example so now let's go to example number three and this one's going to be a little bit more involved.
00:13:00:21 - 00:13:20:18
So kind of get those wheels, turn in for more real world examples. Sometimes these are hard to draw out, but let's go ahead and go through this one because this one has a lot more moving parts than the previous to kind of warming you up. Hopefully your situation isn't super complicated, but if you need to figure this out, I know going through a lot of examples helps.
00:13:20:19 - 00:13:44:13
So let's go ahead and take a look at this. Now I'm going to draw it out two different ways because this is a little bit more complicated. So $500 per month, always on the 15th. So we're going to take 12 contributions of $500, bringing it to 6000 for the year. Our opening balance was 1000 on January 1st. 20, 21.
00:13:44:25 - 00:14:12:08
November to December, our excess was 1000. What I'm saying here is that all through the year we were eligible for those contributions. But when we did our calculations, we actually over contributed by $1,000. So our November and our December contributions were in excess and all of the previous ones. They're okay. They're okay to be in there. They're not in excess.
00:14:12:12 - 00:14:39:27
So we were eligible to contribute 5000 and the additional 1000 was in excess. But we are always making these contributions on the 15th of every month. Now, on November 14th, our balance was $7,000. Why am I using the 14th? Why? Because it's right before our 15th contribution in November and we're going to fix this on March 2nd of the following year.
00:14:39:28 - 00:14:58:19
So I'll put it in 20, 22 and then throw that in there for you and our ending balance was 13,000. So before we go to the worksheet. Let me go ahead and pull this up on a little bit different way of looking at it. And I try to draw out a timeline here. So hopefully this makes sense. We start it with $1,000.
00:14:58:25 - 00:15:25:21
We make January, February, March, April, May, June, July, August, September, October, and November. So our November 11, 14 was $7,000. Then we're going to make our 500. These two were in excess and then we have January and February of 20, 22. Our balance right before we're going to fix this is 13,000. So let's go ahead and plug some of these numbers in here.
00:15:26:07 - 00:15:54:00
So first let's go ahead and zero these out so we can get through this zero these out and where we go 000000 our excess contribution was $1,000 could be is November and December. So that's 500 each $1,000 balances in the date of withdrawal that's going to be our $13,000 which is the balance on March. What did I say before March 2nd.
00:15:54:10 - 00:16:13:06
So the March 2nd is the balance that we're going to look at or March 1st is what we're going to look at. We're fixing this on March 2nd. Same thing. It's our closing balance or date of withdrawal right before our date of withdrawal amount of any withdrawals. We don't have any withdrawals account balance immediately before the excess was made. So that's going to be our $7,000.
00:16:13:13 - 00:16:46:17
And we're saying that was on 11, 14 following day. We make our 500 all our excess contribution. And then the amount of the excess contribution and all subsequent contributions made before the excess removal. Now only bring this up on the screen again. So we made this contribution which was our first excess and we're fixing it on March 2nd. So we have to include 500, 500 and also 500 and another 500 because it's right before we're going to fix it.
00:16:47:07 - 00:17:17:11
I'm certain that somebody is going to get tripped up and think that this is not included when in fact it is. So it's going to be $2,000. So the amount of the excess contribution and all subsequent contributions made before the excess removal So that's going to be $2,000. Any time deposits are going to be zero. So we have our $7,000 and our $2,000 and our adjusted opening balance now is $9,000.
00:17:17:13 - 00:17:44:18
So the big difference here is our excess contribution was $1,000, but our total contributions were 2000. And sometimes when you're looking at this, you might think, well, how are these numbers different? Because you can't possibly make a contribution that isn't in excess after your first contribution, but you can if it's made in the following year, like in this example or in the previous example that we talked about, if we had a rollover contribution.
00:17:44:26 - 00:18:05:00
So either one of those types of contributions will not be in excess. So it's 1000 here. 2000 there. And this makes our math excess contribution total 1000, which is 1000 from here. And then our total earnings was 4000. That's our total would gain and we have to figure out how much of this gain was attributable to the $1,000.
00:18:05:14 - 00:18:36:21
So our adjusted opening balance, which adds everything to So it's going to add all of those contributions to our opening balance. So 7000 plus are 2000. That's where we're getting the 9000. So it's this 7000 a year this 2000 here that equals or 9000, and that gives us a net income attributable of $440.44 bringing the total amount to be withdrawn at $1,444.44.
00:18:36:22 - 00:19:00:04
So we do have one more example, especially if you're trying to figure out how do these rollovers or non excess contributions actually affect the calculation because they do. So let's go ahead and go through an example to show you what that looks like. So if you think there's a strategy that actually might be So let's go ahead and take a look at this.
00:19:00:05 - 00:19:25:24
1231 20, 20 $500, I could have put January 1st. It doesn't matter. $500. January 1st of the year. You put January 1st here. The following day we make a contribution of $500. Basically the same example we've been running through. We have $1,000 in this account. That 1000 turns into $2,000. And 1231. We're going to make another contribution of $500, bringing the total to $2,500.
00:19:25:28 - 00:19:50:05
We immediately realize we made a mistake on January 1st of 20, 22 and we are going to get to work and we are going to fix this. So here's what I want to point out. We have to figure out what the net income attributable is. But here's what's interesting. The net income attributable, you would assume, is associated with the actual investment whether or not it is in cash, it is irrelevant.
00:19:50:05 - 00:20:10:18
Think about that. If you made the contribution, let's say you made that first contribution and we left it in cash. And all the growth from what you're looking at, your statements was attributable to the positions that you bought before you ever made the excess contribution. It doesn't matter. It's all if it's in this single IRA, it's commingled. That means it's all mixed up.
00:20:11:00 - 00:20:30:08
So it does not matter if you made the contribution and left it in cash or you invested it or you had cash and you invested the $500 that you put in there. It doesn't matter. It's co-mingled. So all of the gains will be attributable to either the excess or your existing balance. So that's basically the way that this is going to work.
00:20:30:14 - 00:21:00:02
So that's what I want to point out here. And you're going to notice that last contribution had no growth realistically associated with it. So you might be wondering how is this math calculated? So let's go through it. So the excess contribution amount here is going to be $1,000, $1,000 because we didn't qualify for anything in this example. So we made two contributions, and they're both in excess of $1,000 balance as of the date of withdrawal.
00:21:00:10 - 00:21:38:22
So the date of withdrawal is going to be $2,500 amount of any withdrawals. We didn't do any withdrawals in any of these examples. And number three, the account balance immediately before the excess was made is still our $500 because we made we had $500. There was no growth, we made the contribution $500, and so it's $500. So the amount of the excess contribution in all subsequent contributions before the excess removal, in that case, it's going to be $1,000 because we didn't have any rollovers or any other contribution INS except the excess contributions, which there were two.
00:21:38:27 - 00:22:02:06
So now let's take a look at some of this math. Our adjusted opening balance is 1500 dollars. You start with the $500 and then you add your two contributions, gives you $1,500. We go down here and we see an excess contribution of $1,000 because we made two contributions $1,000 in total earnings or adjusted opening balance. Divide all that by $1,500.
00:22:02:15 - 00:22:38:10
We get net income attributable of $660.67 amount to be withdrawn, $1,666.67. Now here is what is interesting about this example, is the fact that that last $500 didn't do anything for you. So we just contributed at the very last second. There was no growth. But as you're doing this calculation, you're going to realize by making that contribution, it gets tacked on to that opening balance, which then has a greater amount that gets attributable to that excess contribution.
00:22:38:25 - 00:23:20:00
So the excess contributions will take on more weight set another way if we never made that contribution. The only $500 of the gains would have been associated with the excess contribution. But because we made that last $500 contribution and it was in excess, that means more is going to be attributable. Because in that instance, we see we see that our net income attributable here is $666.67 rather than $500, which might be the more logical way of looking at this, that it would be $500, but it's not at $667 if you're rounding, and then you're going to add that to the total excess contribution.
00:23:20:01 - 00:23:40:14
So hopefully this examples have helped and used the blog post, use the worksheet. Go, go slow. Do it possibly on a weekend to make your life a little bit easier. And if you have any questions comments, let me know in the comments. Down below. Check out the blog post or leave that description at the bottom as well. And if you've enjoyed this video, be sure to subscribe and leave your comments down at the bottom.
Download the Roth IRA excess contributions worksheet.
Download the worksheet above. You can watch the video or use the following guide to complete the removal of excess contributions worksheet.
Net Income Attributable Formula
The formula below is used to calculate the net income attributable (the gains associated with your contribution) to a returned or recharacterized IRA contribution. The steps below will use a worksheet to help guide you through the calculation so you don't have to do the math.

Pro Tip: There are two parts to the amount being removed or recharacterized, the excess contribution and the net income attributable. They are not the same. The Excess contribution is the amount you overcontributed and the net income attributable is the amount of gains associated with the excess contribution.
00:00:00:03 - 00:00:19:11
In this video. I'm going to walk you through the calculation for the net income attributable formula for a removal or recapitalization of an IRA or a Roth IRA contribution. And I'm also going to show you a really easy worksheet so you don't have to go through any of this math, but I'm going to explain how it works anyways.
00:00:19:22 - 00:00:40:05
But first, I'm going to show you some resources on our blog, theincrediblepenny.com. And this is The Post, How to Fix the Excess Roth IRA contributions and a step by step guide. But this is also the same formula if you have an IRA excess contribution that you can walkthrough. And if we scroll down, we're going to see the button here, download the worksheet, which I'll go through in just a second.
00:00:40:15 - 00:01:12:15
But let's take a look at the formula first on this post with the net income attributable formula. And you could see the net income equals the contribution times the adjusted closing balance, which I'm going to explain what that is, minus the adjusted opening balance divided by the adjusted opening balance. But I do want to point out before we go through the worksheet and the easy calculation is that there are two parts to the amounts being removed from the recharacterize or the removal of your contributions.
00:01:12:23 - 00:01:38:23
And that is the excess contributions versus the net income attributable. So the net income attributable is the gains associated with your excess contribution. And it's it's important to understand that they're different. The excess is what you contributed or over contribute it into the IRA or Roth IRA. And the net income attributable is or the gains associated with the excess.
00:01:38:29 - 00:01:54:20
Now you're going to end up taking out both. But you have to understand there is a difference to both of those numbers. Now, let's go ahead and pull it up on the screen to go through this worksheet. So just click on that button and download the worksheet and you can walk right through it. I'll leave a link in the description at the bottom.
00:01:55:01 - 00:02:16:21
Let me go ahead and zoom in here and scroll down to the formula. And again, you can see it right up here, the net income attributable formula. It's written differently. It's the exact same formula. So it's net income attributable equals excess contributions times the total earnings divided by the adjusted opening balance. So what do we need to do first?
00:02:16:21 - 00:02:33:14
We need to figure out what our excess contribution amount was. Now I'm just going through the net income attributable formula. So you need to figure out based on your income and have other videos and other resources, check my channel and the link in the description at the bottom, but you need to figure out how much your excess was.
00:02:33:21 - 00:02:54:04
Let's say that we contributed $500 too much to our IRA, the balance as of the date of withdrawal. So now we need to jump to number one balances the date of withdrawal. Let's see that balance on the date you're removing. It was $8,000 and I'm just making these numbers up as we go just so you can see how this all works.
00:02:54:15 - 00:03:14:24
Number two amount of any withdrawals, it's probably rare that you had to withdraw from any IRA or this IRA and it is only the IRA that has the excess contribution that you're going to be working with. It doesn't matter if you have multiple IRAs, it's only the one with the excesss, line three the account balance immediately before the excess was made.
00:03:15:03 - 00:03:37:28
So this is the day before the closing price, on the day before you made your excess contribution. So if you made it really early in the year, let's say January 15th, you're going to look to January 14th. Let's say you did it in November 15th, then it's going to be November 14th and you're going to look at the closing price on that date and you're going to add all the money up in the entire account.
00:03:38:06 - 00:04:00:10
That is the account balance immediately before the excess was made. Now, it is going to be your last contribution So let's say that I was making contributions throughout the course of the year. Let's say you made $500 per month and you only had one excess contribution. Then that would be the one made in December. It is the last contribution in the tax year that is your excess contribution.
00:04:00:22 - 00:04:28:04
If you had two contributions in that same example, you would go to November, December. It was three years ago, October, November, December. You're never going to take out the first one and leave the last one in there. That's how the formula works. Line three Account Balance. Immediately before the excess was made, let's say that was $4,000, and the amount of the excess contribution and all subsequent contributions made before the excess removal Just so you know, subsequent means after.
00:04:28:04 - 00:04:49:21
So what this means is if you made any contributions, including rollover contributions into this account, that would go right here. But we're just going to go ahead and put $500. Why? Because it says the amount of the excess contribution, which was $500, but we didn't make any contributions after that time. So we're just going to put $500 in there.
00:04:50:01 - 00:05:18:24
Let's say you're fixing this in January and you made a January contribution right before you went to go fix it. You would include it because you're doing this right before the excess removal, even though any additional contributions wouldn't get added to the excess contribution any time deposits like CD surrenders or annuity surrenders. So we're going to say zero, it's unlikely you're going to have it, but if you do, that's what it's referring to.
00:05:19:01 - 00:05:42:01
Now we're going to scroll down and see how it plugs in the formula, the numbers into the formula We have our $500 excess contribution $3,500 in total earnings. And then we have our adjusted opening balance that adjusted opening balance simply took all contributions and all subsequent contributions and added it to the opening balance. That's why it's called the adjusted opening balance.
00:05:42:07 - 00:06:21:06
And it explains it right here. Now, our net income attributable is $388.89 means that we need to add our $500 to our three $88.89 and we get a total amount to be withdrawn of $888.89. If we quickly go back to the blog post if you have more questions, I do a full walkthrough with more explanations. In addition, I also have several videos on this page that you can watch for more examples on the net income attributable and the excess contributions and how to remove them, and that is to walk through with net income attributable.
00:06:21:06 - 00:06:24:06
Unknown
If you've enjoyed this video, be sure to subscribe and leave your comments on the bottom.
1. Enter the balance as of the date of withdrawal.
This is the balance today or when you're going to withdraw the funds from the Roth IRA. If it's not done today, then you can't complete this worksheet. Complete it right before you want to remove the excess contributions.
Pro Tip: Do this worksheet on a Friday after the market closes so you have the weekend to get the math done and submitted Monday morning for removal. The numbers won't change over the weekend so it gives you time to check and get it done correctly.
Usually, you can get your account balance through your broker-dealer or online trading portal.

2. Add the amount of any withdrawals (including transfers out of the account) taken after the excess contribution and before the excess removal.

You can find your withdrawals in the transaction history on your account statements or online portal. If you run a sort on your transaction history, you may see something like this and will need to choose the withdrawal types. Your online account may show different categories but make sure it's all the withdrawal types of transactions.
You will also need the contributions (deposits) for step 4.

Your account statements can also be used to find withdrawals. They will look similar to this, showing withdrawals, but check all your statements, so you don't miss a withdrawal.

Using an online portal and account statements together may help verify that you didn't miss any transactions. Go slow and take your time.
Pro Tip: Keep copies of your calculations and the numbers you used with your tax documents. If you are audited or need to review your excess contribution math, you will have it.
3. Account balance immediately before the excess was made.
This step is usually more time-consuming than step #1 because you will likely need to look up each position's price immediately before the excess was made.

How to calculate your starting account balance
First, find the price of each position you own and multiply it by the number of shares. The share price needs to be right before your first excess contribution.
For example, if you owned Apple stock, look up the ticker Aapl, and find the share price right before the date of your first excess contribution. Use the closing price.
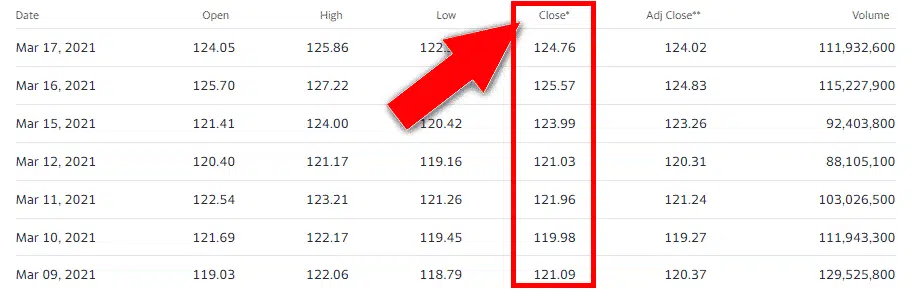
You can use any reputable site to find the share price, such as Yahoo Finance, or your broker-dealer may have a tool or online portal to look up historical data. On Yahoo Finance, if you looked up the Apple stock price on March 12, 2021, the price was $121.03. If you owned 100 shares that equals 100 (shares) x $121.03 = $12,103.
Pro Tip: Everything is commingled for excess contributions. It does not matter if you invested the excess contribution or left it in cash. Regardless, a portion of any growth or loss will be associated with the excess contributions. The growth associated with your excess contribution is called income attributable.
4. The amount of the excess contribution and all subsequent contributions made before the excess removal.

If you have multiple contributions including rollover contributions you will need to add them all up. Only add the contributions from the date of the first excess contribution up to the date you are removing the excess contribution.
For example, if you contribute $500 monthly to your Roth IRA and your November and December contributions were excess contributions include the $500 per for each of these months. In addition, if you also rolled over $10,000 into the Roth IRA, include that. In this example, your starting balance will include $500+$500+$10,000 = $11,000 plus your initial account balance.
If you also contributed $500 in January of the following tax year before you removed the excess contribution, you will include that as well.
5. Any time deposit (or other investment) penalties that will be applied due to the excess removal.

If you're invested in securities such as a CD you may have time deposit penalties. Add them up for step 5.
Example #1 Roth IRA Excess removal worksheet
In this example, I contribute $6,000 to the Roth IRA and the account grows to $7,000. There was no existing Roth IRA before the excess contribution. The modified adjusted gross income is $500,000, way over the income limit, therefore the full $6,000 contribution was considered an excess contribution.
The entire balance will need to be removed and here is the correlating worksheet. If all your contributions are excess contributions you can just remove all the money from the account without doing these calculations.
We are going through this as an example to show how the math is done.

The growth of this Roth IRA is 100% attributable to the contribution since there was no account balance immediately before the excess was made and no additional contributions before the excess is removed.

Example #2 Roth IRA Excess removal worksheet
In this example, we will contribute $500 monthly to the Roth IRA but only the last $500 will be the excess contribution.
The excess contribution amount is $500 and the net income attributable is $83.33. Adding them together brings the total amount to be removed to $583.33.

Download the Roth IRA excess contributions worksheet.
Method #2 Roth IRA Absorb to next year
00:00:00:01 - 00:00:17:13
If you over contributed to your Roth IRA, here's an easier way to fix it. According to IRS publication 590, you may be able to apply it to a later year if the contributions for that later year are less than the maximum allowed for that year. But there is one catch. This method lets you avoid making a withdrawal.
00:00:17:14 - 00:00:42:12
It doesn't, however, let you avoid the 6% tax on any excess contributions remaining at the end of the tax year. So you'll pay your 6% tax penalty on the excess contribution. But that is not on the growth portion Also called the net income attributable. You can just leave it all in there. And next year, as long as you can make the amount of the excess contribution as a regular contribution, it'll be absorbed into your Roth IRA.
00:00:42:13 - 00:00:57:07
But if you can't make that full contribution as the excess contribution, any amount that's leftover, we'll have another 6% penalty each and every single year until the full amount of the excess contribution is absorbed in the Roth IRA.
The absorb method moves the excess contribution to the following year. If the excess is still more than the following year's allowable contribution limit then the amounts will be carried forward until the excess is completely absorbed. The 6% penalty is assessed on the excess amount each year and calculated based on the excess remaining.
For example, if you contributed $15,000 to your Roth IRA in 2021 when you were eligible for a maximum contribution of $6,000, then $9,000 is the excess contribution. In 2022, if you were again eligible for a $6,000 contribution, you would still have $3,000 carry forward to 2023. The 6% penalty would apply to the $9,000, then again to the $6,000, and finally to the remaining $3,000.
It's a costly mistake and should be corrected as soon as possible.
Note, that the growth portion, if any, is not included in this calculation and remains in the Roth IRA. The penalty is calculated and paid using IRS form 5329 for each year.
Method #3 Roth IRA Recharacterization
The recharacterization method moves the excess contribution from the Roth IRA to the traditional IRA. The same calculation above, using the net income attributable is also completed in this method. The amount that will need to move from the Roth IRA to the traditional IRA includes the excess and the net income attributable. In the case of a loss, the amount moved will be less than the original excess contribution.
The benefit of recharacterizing your Roth IRA excess contribution over removal is the avoidance of taxes on the distribution. The removal method may have taxes and penalties applied whereas, the recharacterization method would not.